First, let’s look at some basic project budget principles: The total loan amount cannot exceed the projected appraised value of the property, once the renovations are complete. That appraisal takes into account all of our planned improvements to the house (see also 04/12/2009 post) and came in at $280,000.
If we subtract the purchasing price of $60,000, we are left with $220,000, which is the maximum amount that our bank (ShoreBank) would lend us for the green rehab.
Cathy and I feel that $220,000 for the rehab is more than we want to take on right now. We went through our personal finances with a fine tooth comb, looked at various mortgage scenarios, estimated monthly payments, and decided that we can manage a rehab loan amount of $160,000 right now.
This $160,000 is one piece of the puzzle. I now have to get the other piece – what that $160,000 is actually buying us. We have a number of ball park estimates from contractors and vendors (see also 05/13/2009 post), which are all very conservative, because of the limited information I could provide at the time I requested the information.
How would I know that these estimates are conservative? By talking to friends, industry contacts and other homeowners who actually had, for example, a base board heating system installed. Their project may be different from ours, but the aggregate pricing information gives us the clues.
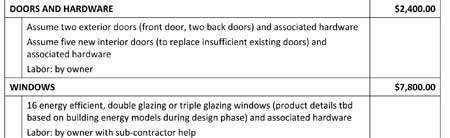
In short, our project budget (see also: 3141 ball park project budget) is based our interpretation of the conservative estimates we received. It is a product of our combined guesstimates, leaving a lot of questions unanswered, such as how the work we plan to complete ourselves impacts the budget.
We hope to completely rehab the basement and 1st floor for the $160,000. What can we really get for that money? Your guess is as good as ours, and you can witness this unfolding over the next few months on this blog.