Tag Archives: house hunting

Buying a foreclosure – Part 5

Time is ticking away and we are trying to get a handle on what has to be put together, and when. Not an easy process if you are a first-time buyer. We finally (sort of) got a schedule from ShoreBank:

  1. Determine project budget
  2. Commission appraisal of property
  3. Take loan application to ShoreBank’s loan board for approval

Project budget

I scramble to put a budget for our green rehab together. We need to determine how much money is going into the green rehab to set the total loan amount (purchase price + rehab budget).

Fortunately we have our project rationales and principles in place to guide us through this process. We shared this information with developers, green building experts and friends that had rehabbing experience and could help us with our project budget development. We also contacted various specialists (such as energy experts), vendors (such as solar hot water), and contractors for pricing information.

Appraisal

Once we have the budget number, there is no guarantee that ShoreBank will lend us that much. The upper limit of the loan amount is determined by two factors. The first one – how much we feel we can take on – is controlled by us. The second is determined by an appraisal commissioned by ShoreBank. This appraisal takes into account all of our planned improvements to the house – it is a post-improvement appraisal.

Our worry is that the dollar amount of the post-improvement appraisal will be lower than our project budget. That would through a big old wrench into the process. We would need to conduct more pricing research to figure out how to cut our budget with the closing date fast approaching.

To get to the appraisal commissioned, ShoreBank was pressing for our project budget and I was able to deliver half a day early. That did not help us. It turned out that the appraisal would take longer than usual due to the sustainable scope of our rehab plans and the associated extra research.

Loan approval

ShoreBank’s loan board in Chicago currently meets once a week (every Thursday) to review and approve loan applications. Phil (our banker) worked hard on getting our application in front of the board as soon as possible. He needed the appraisal on Wednesday for the Thursday’s meeting. But unfortunately the appraisal arrived on Thursday and we missed this week’s opportunity to have our application reviewed.

The bad news is that this set us back a whole week to next Thursday. That is the same Thursday on which our closing should have taken place! The good news is that the appraisal was actually higher than our requested loan amount.

We now have to worry about pushing the closing date back again. We were not sure if the seller would just cancel the deal or go along with another extension. This is where we could rely as usual on Joe Ziccardi (our attorney). He managed once again to have the seller agree to the new closing date and to have any penalties for the delay waived. Thank you Joe!

We coordinated with ShoreBank to make sure that the new closing date was realistic: The seller had insisted that this was the last and final extension granted.
Related posts:

Buying a foreclosure – Part 4

With a ratified and executed agreement in hand, we immediately contacted ShoreBank. The first question Phil (our banker) asked: “When is your closing date?” Our answer: “In one week.”

I think I heard our banker Phil fall out of his chair. He informed us with great urgency that this is an unrealistic time frame. He would need about 30 days to get the loan application approved and all other paperwork in place.

Of course that’s not what we wanted to hear. On the other hand, we know that this is an unusual project that may require more than the usual time. Life would be easier if we could finance the purchase with our own cash (a practice not that uncommon as we heard on This American Life). But how would we pay for the rehab? You know, waiting for paperwork to get done suddenly doesn’t sound that bad.

Except – what is our convoluted seller with his erratic response times saying to this? We had the vision of the deal floating away from us again. This is where Super Joe (our attorney Joe Ziccardi) came to the rescue. He managed again to get the sellers attorney on the phone and re-negotiated the closing date. Not only was he able to get the date pushed by three weeks, we were also spared any penalties for the delay. Thank you Joe!

Three weeks was less than the 30 days ShoreBank asked for. But having gotten to know the seller, we were in no mood to push this any harder.

If you live in the Chicago area and need an excellent Real Estate attorney, we recommend you contact Joe:

Related posts:

Buying a foreclosure – Part 3

We are happy about the recent price drop for what we started calling “our two-flat” and submitted a new offer for the $60,000 asking price. This time around, things happened at the speed of light. Not only did we get the usual verbal confirmation of the offer acceptance, we actually got the sellers counter offer and addendum within days!

Seller’s counter offer and addendum

What is a seller’s counter offer and addendum? We initially submitted with the help of Michael (our Realtor) a standard Chicago Real Estate contract with a preapproval letter from a lender and a copy of our earnest money check. That package is basically our offer. If the seller accepts our offer, they issue their own contract, comprised of a counter offer and an addendum. Most people think of a counter offer as being related to the price of the property, but this negotiation has nothing to do with the price, which is set.  The counter offer has to do with the seller’s contract, which absolutely supersedes our original contract, except for those terms that are not inconsistent with the sellers counter offer and addendum. Got it? To figure out what supersedes what, some careful reading is required.

Response to counter offer and addendum

That is exactly what we did and identified a number of items that were inconsistent, did not make sense, or that we disagreed with. Our attorney, Joe Ziccardi, summarized those items in a response to the seller, basically requesting changes to the counter offer and addendum.

Ratified and executed agreement

Only a couple of days later (yes – things suddenly started to move fast!) we got the fully ratified and executed agreement. This basically means that our response or request for changes to the counter offer and addendum were accepted and all parties are in agreement on the terms. It was almost too good to be true… except that it the “fully ratified and executed agreement” had no reference to our response and request for a few changes to the counter offer, and did not even acknowledge  receipt of our request.

The reference finally arrived a few days later from the seller’s attorney, with six out of our seven request for changes declined. Initially, we were not sure what to make of it, but began to realize that these items could be resolved through negotiation or a request of clarification. The problem is that like with the seller’s agent, the seller’s attorney was not very responsive. Thanks to the persistence of our attorney, he finally reached a warm body picking up the phone and worked his way to the person who dealt with our case. Not only that, but Joe was able to get clarification on all the questions and disagreements we had. A few more days of nail biting and we were finally in possession of a truly ratified and executed agreement – hooray!

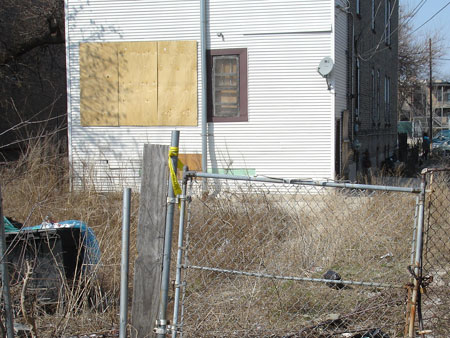
We now were also finally able to secure the building by boarding up the back porch windows. You have no idea how much weight this took of our shoulders!  (Especially after we got down off the ladder after holding ¾” sheets of plywood up there in the rain while we secured them.)

back-porch-boarded-up

Related posts:

Buying a foreclosure – Part 2

One might think that a bank that owns a foreclosure would like to sell it quickly to take it off the books. Our experience so far has been the opposite, after two of our offers, both for just a little more than the asking price of $75,000, were canceled for no good reason.

When Michael, our Realtor, got word of the second cancellation, both Cathy and I were out of town on work trips – and both were incommunicado. This is where a good Realtor is priceless. Michael knew what we wanted and immediately resubmitted the offer again on our behalf. Thank you Michael!

And this is where it got unreal: While preparing the offer for re-submittal, Michael found out that the asking price had dropped by another whopping $15,000, down to $60,000 – because the bank was unable to unload property! Never mind that we offered twice to buy it for $75,000. But who are we to complain. We started joking that if we kept re-submitting often enough, the seller may give us money if we take the property.

That said, we were unsure what to make of this price drop. Suspicion crept in. Like my dad said when we told him the story: “That can’t be right! Since when is a bank giving away money – and as much as $15,000?” Is this another instance of too good to be true?

We went back into research mode. There was no further damage to the property – thank God. We found out which bank actually owns the foreclosure, and got a better understanding of the convoluted paper pushing process. It turns out that the seller’s agent never really talks to a person on the bank’s side. They just input data into an online system, which is received at the bank and “processed”. This could happen in any office of that bank, of which there are numerous nationwide. It appears there is no one person assigned to a case.

You hear a lot about the banks not being ready for this growing wave of foreclosures. We got the impression that the left hand did not know what the right hand was doing – or that there even was a right hand. Understanding this, we felt more at ease with the price drop and that it actually was for real.

Related posts:

Buying a foreclosure – Part 1

Now that we put another offer down on the foreclosed two-flat we like so much, we have an interest in having the property secured (see also 04/06/2009 post). Vacant, unsecured buildings (often foreclosures) are a big problem for the City of Chicago. They invite illegal activities such as prostitution, drug dealing and drug manufacturing, and often become a safety and fire risk. The city takes this very serious and has an abandoned building program where such nuisance properties can be reported.

back-porch-no-window

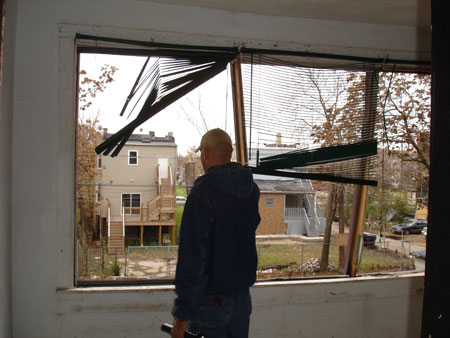
The back porch windows at our two-flat are knocked out and relatively easy to climb through. Michael Salvatori, our Realtor, contacted the seller’s agent and was told they can do nothing to secure the property. We learned that the seller’s agent had literally hundreds of foreclosures to deal with and was completely overwhelmed. Never mind that the seller does not want to spend any money on the property…

We decided that we’d have to take it upon ourselves to secure the property. That said, we have to wait until we have an executed and ratified agreement:

  1. We did not want to run the risk of trespassing.
  2. We did not want to invest in securing the building without some certainty that we actually get it.

What happened next is what we call the dance:

  1. Michael received a phone call informing him that our offer was accepted.
  2. Excellent – until the next phone call came, asking for our final and best offer. This had déjà vu written all over it (see also 04/06/2009 post).
  3. We were confident that this was just standard protocol by the seller and raised the offer by a few hundred dollars to show our good intent,
  4. Upon which Michael received another verbal confirmation that our offer was accepted.
  5. All we need now is the paperwork, the executed contract.

We waited and got more and more nervous because we were about to leave for a two-week vacation. We were  still waiting as we packed and went to the airport. We waited while we were gone, and we returned and waited some more. Finally, one day prior to the proposed closing date, Michael was able to reach the seller’s agent, only to learn that our deal got canceled! Why? Your guess is as good as ours.

We asked, “Can we submit the offer again?” The answer was yes and Michael wasted no time doing so on our behalf. And we started the dance again:

  1. Michael received a verbal confirmation of acceptance
  2. We received another request for our final and best offer
  3. We raised the price by a few hundred dollars
  4. Michael received another verbal confirmation of acceptance
  5. And we started waiting again for the paperwork

Except, this time Michael received a phone call from the seller’s agent (I had given up to believe that this could actually happen), informing him that our deal was once more canceled! Still no real good reason as to why.

Does the bank, who has ownership of this property, really want to sell it? We constantly hear in the news how bad these foreclosures hurt the banks, and how desperately they would like to unload them. But we also hear that they have difficulties to keep up with all the paperwork. May be that is where we keep getting stuck with our purchasing attempts – in that huge pile of paperwork.